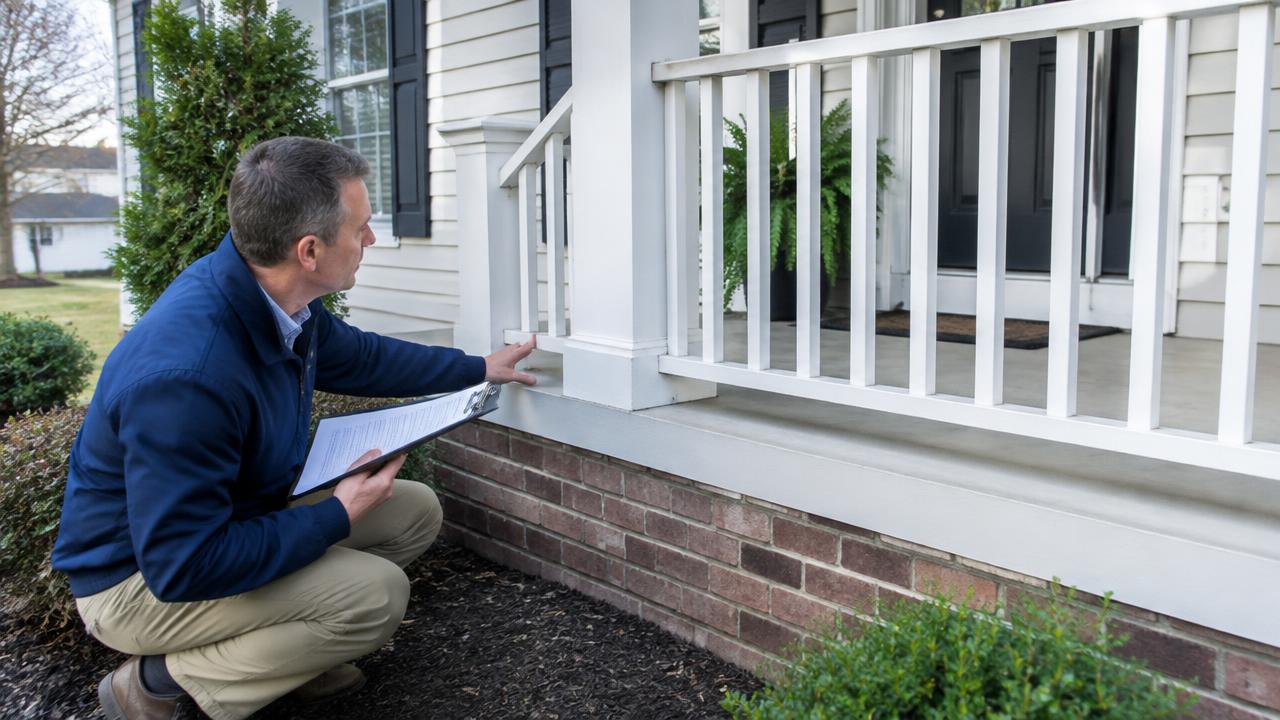
When you are buying, selling, or refinancing a home in Oakland, Wayne, Macomb, or Washtenaw County, hearing the phrase *"the appraisal failed"* sounds terrifying.
In reality, a real estate appraisal isn't a pass-or-fail test in the traditional sense—at least for private-party appraisals (like estate, trust, divorce, or tax appeal valuations, where an appraiser can always determine an "As-Is" market value regardless of condition).
However, when a mortgage lender is involved, an appraisal can derail or pause a loan in two very specific ways:
- A Value Shortfall: The appraised market value comes in *lower* than the agreed purchase price (or refinance target).
- Property Condition & Safety Flags ("Subject-To" Repairs): The home fails to meet minimum health, safety, and structural soundness requirements for FHA, VA, or Conventional (Fannie Mae / Freddie Mac) underwriting—meaning the bank refuses to fund the loan until specific repairs are completed and re-inspected.
Reviewing the 8 most common issues that "fail" or hold up a mortgage home appraisal in Michigan—and how you can fix them before the appraiser ever pulls into your driveway—will keep your transaction on track.
Conventional vs. FHA & VA Appraisals: The "3 S's" Rule
While Conventional loans primarily focus on major structural integrity and overall marketability, FHA and VA loans require the appraiser to evaluate HUD's strict Minimum Property Standards (MPS) built around the "Three S's":
- Safety: Protecting the health and safety of the occupants.
- Security: Ensuring the property can be locked and secured properly.
- Soundness: Verifying the physical structure and mechanical systems are free of major defects.
8 Issues That Will Flag or "Fail" a Mortgage Appraisal in Michigan
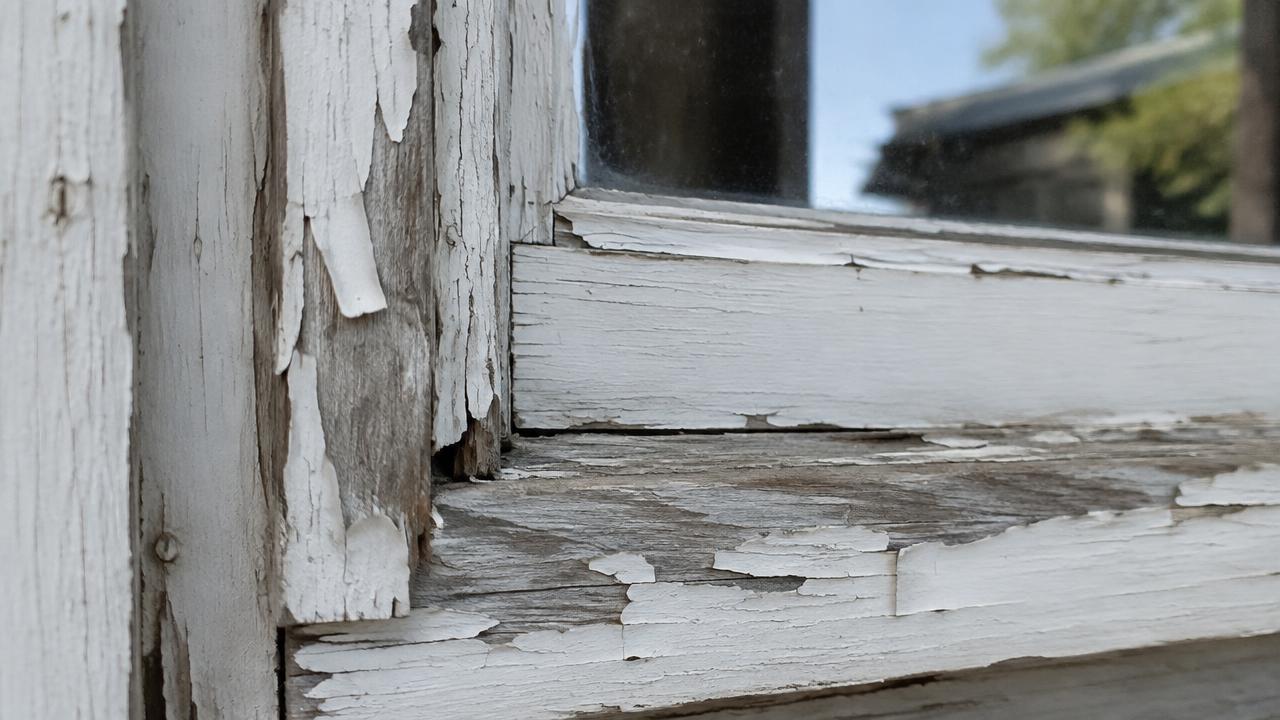
1. Chipping or Peeling Paint on Homes Built Before 1978 (The #1 FHA/VA Flag!)
In older, established Metro Detroit communities like Royal Oak, Berkley, Birmingham, Ferndale, Grosse Pointe, and Dearborn, thousands of homes were built prior to January 1, 1978. For any pre-1978 home, FHA and VA guidelines treat *any* chipping, flaking, or peeling paint—inside or outside, including window sills, porch steps, detached garages, and sheds—as a potential lead-based paint hazard.
- The Fix: Scrape, prime, and repaint any peeling wood or trim, and sweep up all paint chips before the appraisal appointment.
2. Missing Stair Handrails (3 or More Steps)
One of the easiest—and most frustrating—reasons an appraisal gets flagged for a mandatory repair re-inspection is a missing handrail on basement stairs, porch steps, or deck stairs. If a stairway has three or more risers, installing a secure handrail takes 30 minutes and prevents a $150–$200 lender re-inspection fee.
3. A Failing Roof (Less Than 2 Years of Remaining Life)
Appraisers inspect the roof from the ground and check the attic for active water leaks, daylight showing through roof sheathing, or severe shingle curling and missing tabs. For FHA and VA loans, the roof must have at least 2 years of remaining physical life and cannot have more than three layers of roofing material.
4. Utilities Turned Off or Non-Functional Heat (Critical in Michigan!)
In Michigan’s climate, every habitable room must have access to a permanent, working heat source capable of maintaining a safe indoor temperature. If a home is vacant (such as an estate property) and the water, electricity, or gas furnace is turned off on inspection day, the appraisal is an automatic fail for lending until utilities are restored and re-tested.
5. Exposed Electrical Wiring, Missing Outlet Covers & Water Heater Valves
Exposed live wires (often found in unfinished Michigan basements or garages), open junction boxes, antiquated hazardous panels, or a water heater missing its Temperature and Pressure Relief (TPR) valve and discharge pipe will trigger safety repair flags.
6. Structural Foundation Cracks, Standing Basement Water, or Active Mold
Minor hairline settling cracks in a poured concrete basement wall are common in Michigan clay soil. However, horizontal bowing walls, severe stair-step block cracks, standing water in the basement or crawlspace, or visible black mold and wood rot will require a structural engineer's clearance or professional remediation before a lender will close.
7. Broken Window Panes, Rotting Outbuildings, or Trip Hazards
Cracked glass window panes, severely heaved concrete walkway slabs that create trip hazards, or a leaning, rotting backyard shed in danger of collapse will be flagged under FHA/VA safety and soundness rules.
8. "Value Failure" — Overpricing Above Verified Comparable Sales
Even if a house is in spotless physical condition, a purchase transaction can still "fail" the appraisal if a buyer bids $550,000 on a house where every verified comparable sale in the neighborhood closed between $495,000 and $510,000. Because banks base your loan strictly on the lower of the purchase price or appraised value, an unsupported contract price creates an immediate cash shortfall at the closing table.
How to Prevent Appraisal Surprises Before Listing or Buying
At Michigan Appraisal Team Inc, principal appraiser Joe Bahri helps Michigan homeowners and buyers avoid appraisal failures in two ways:
- Order a Pre-Listing Appraisal: Before you put your home on the market, we inspect your property, measure your exact ANSI Z765 square footage, apply modern UAD 3.6 component ratings, and point out any easy 20-minute safety fixes so your home sails through the buyer's bank appraisal.
- Work With an Appraiser-Realtor: When you buy or sell through Joe Bahri at Max Broock Realtors, you have a State Licensed Appraiser protecting your contract from Day One—spotting FHA/VA property red flags during showings and pricing listings so they never fail underwriting.
- Call Us Directly: (248) 798-4446
- Email: info@michiganappraisalteam.com
- Office: 6775 Daly Road, Suite 104, West Bloomfield, MI 48322
- Get Started: Request a Pre-Listing or Home Appraisal or learn more about our Real Estate Services with Max Broock Realtors.